


TLDR
- Micron (MU) stock rose over 1% in Friday premarket trading to $989.50, lifted by a stronger tech backdrop
- China’s CXMT is reportedly planning a NAND flash memory R&D production line in Beijing, expanding beyond its DRAM focus
- NAND flash accounts for about 25% of Micron’s revenue; Micron holds roughly 15% of the global NAND market
- The DRAM market grew 57% and NAND grew 70% quarter-over-quarter in Q2, suggesting strong overall demand
- Micron’s earnings report is due September 30, with analysts holding a Buy consensus and an average price target of $1,521.74
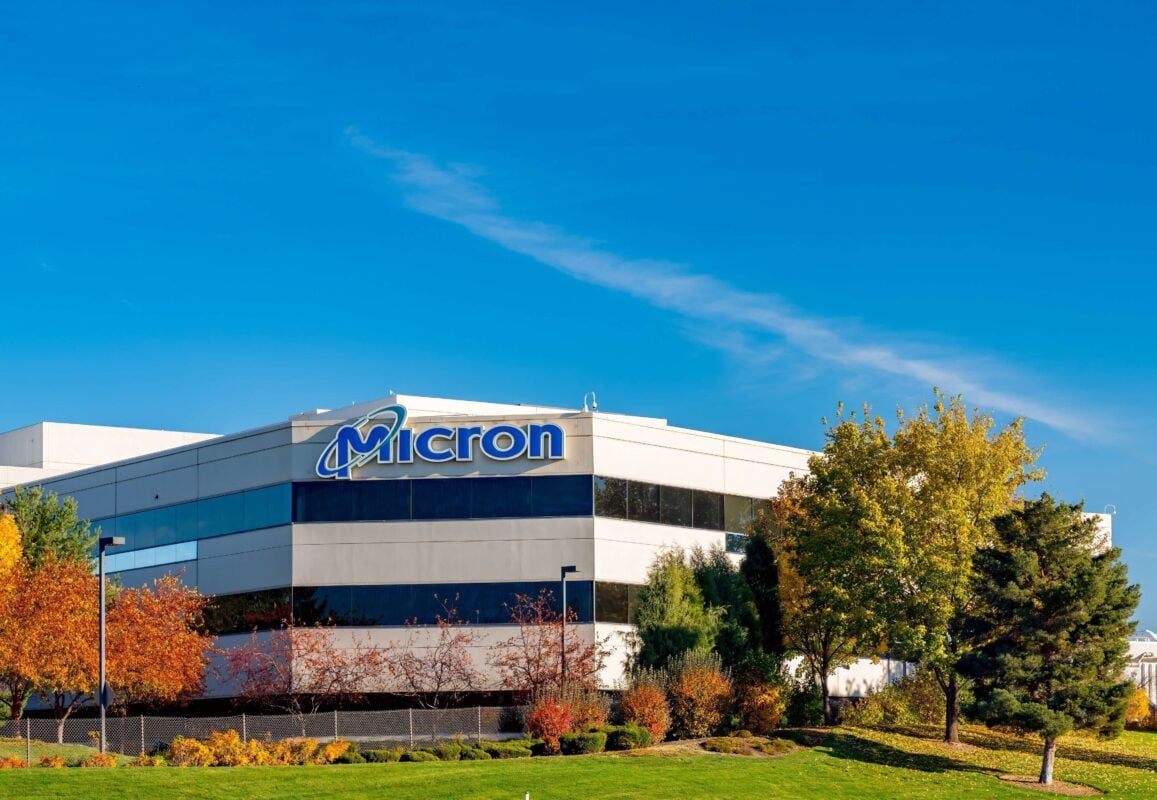
Micron (MU) stock climbed 1.23% to $989.50 in Friday premarket trading, with the broader semiconductor sector catching a bid as Nasdaq futures gained 0.54%.
The move came alongside fresh headlines out of China. CXMT, the Chinese DRAM specialist whose stock surged 466% on its Shanghai debut earlier this year, is reportedly planning to build a NAND flash memory R&D production line at a new factory in Beijing, according to Reuters.
That is a meaningful pivot. CXMT has been a DRAM-focused company, but moving into NAND flash would put it in direct competition with Micron, SK Hynix, and domestic rival Yangtze Memory Technologies.
YMTC already holds 14% of the global NAND market as of Q2, according to Counterpoint Research. Adding CXMT to that mix would make the sector more crowded.
Currently, Samsung leads the NAND market with a 28% share, followed by SK Hynix at 19%. Micron sits at roughly 15%, and Sandisk at 11%.
NAND flash makes up around 25% of Micron’s total revenue, so any competitive pressure in that segment is worth watching. SK Hynix carries a similar exposure.

China Threat in Context
That said, there is no confirmation yet on when or if CXMT will move into commercial NAND production. Analysts note that if it does, the company would likely target the domestic Chinese market first, which could make YMTC a bigger casualty than Micron.
Micron also has less NAND market share to lose to Chinese competitors than SK Hynix does, which offers some relative cushion.
The broader memory market is still growing fast. DRAM grew 57% quarter-over-quarter in Q2, and NAND grew 70%, Counterpoint data shows. That kind of growth leaves room for multiple players to generate strong revenue even as competition rises.
U.S. Expansion and Analyst Views
On the domestic front, Micron is building out U.S. production capacity. The company has an advanced memory fabrication facility under construction in Boise, Idaho, and another in Clay, New York.
The expansion comes as NVIDIA and AMD seek to lock in additional memory supply amid tight market conditions.
Technically, MU is trading 3.5% above its 20-day moving average of $957.53 and 6.9% above its 50-day average of $926.77. Its RSI sits at 53.95, a neutral reading.
Key levels to watch: $1,012 as resistance and $887.50 as support.
Analyst sentiment remains firmly positive. Micron carries a Buy consensus with an average price target of $1,521.74. Mizuho kept its Outperform rating but trimmed its target to $1,300. New Street Research upgraded to Buy with a $1,250 target. Citigroup maintained Buy at $1,150.
MU stock has gained 478.78% over the past 12 months.
Investors will get their next major catalyst on September 30, when Micron reports earnings.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants