


TLDR
- Generac stock jumped 35% in premarket Thursday after announcing a long-term generator supply deal with Amazon
- Initial deliveries are valued at $2.4 billion across 2027 and 2028
- Amazon gets an equity warrant for up to 1.69 million GNRC shares at around $201 each
- The deal confirms Amazon as Generac’s second hyperscale data center customer
- Barclays reiterated its Equalweight rating with a $278 price target following the announcement
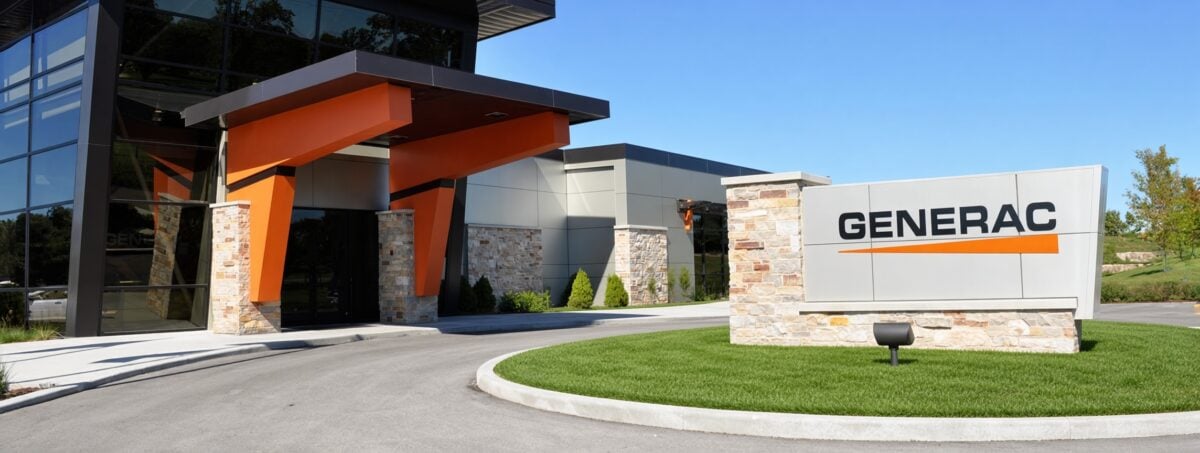
Generac (GNRC) stock jumped 35% in premarket trading Thursday after the company disclosed a long-term supply agreement with Amazon for backup generators destined for data centers. The stock was trading around $235 in premarket, which would put it roughly 72% above its 2025 closing price of $136.37.
The deal covers initial generator deliveries valued at $2.4 billion, spread across 2027 and 2028. That averages out to about $1.2 billion per year, a large number relative to Generac’s total 2025 revenue of $4.2 billion.
The agreement was disclosed in a Securities and Exchange Commission filing Wednesday evening. It identifies the customer as Amazon Data Services, the same “second hyperscale customer” Generac had referenced back in July without naming.
As part of the deal structure, Amazon receives an equity warrant allowing it to buy up to 1.69 million GNRC shares at roughly $201 each. That represents about 2.6% of fully diluted shares.
Around 308,000 of those shares vested immediately upon signing. The rest vest incrementally as Amazon and its affiliates hit cumulative spending milestones on Generac generators, up to a total of $8 billion. Full vesting runs through 2033.
Data Center Business Gaining Ground
Generac’s data center exposure has been building for some time. In its second quarter 2026 report, commercial and industrial sales rose 29%, and the company’s data center backlog had already hit around $1.6 billion before this deal was even disclosed.

The Amazon agreement is global and covers data centers outside the United States as well.
On the earnings front, Generac beat profit estimates in Q2, posting adjusted earnings of $2.91 per share against an estimate of $2.00. Revenue came in at $1.17 billion, slightly below the $1.18 billion forecast. A tariff refund contributed to the earnings beat.
Analyst Reaction
Barclays kept its Equalweight rating on GNRC after the announcement, holding its price target at $278.
Cantor Fitzgerald was more upbeat, raising its price target to $333 and pointing to strength in the data center segment as the reason.
Needham reiterated its Buy rating with a $282 target. The firm highlighted the tariff refund as a factor in the strong Q2 results.
GNRC closed 2025 at $136.37 and had gained about 28% through Wednesday’s regular session before the after-hours news hit. The stock had previously reached a 52-week high of $296.44 on June 25 before falling around 41% through Tuesday.
InvestingPro’s analysis flags GNRC as trading below its Fair Value estimate, with the stock carrying a P/E ratio of 39.97 and a market cap of $10.33 billion.
Barclays reiterated its $278 price target following the deal announcement, reflecting a more cautious stance compared to Cantor Fitzgerald’s $333 target.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants