
TLDR
- Western Digital (WDC) trades near $376 to $379, nearly 50% below its June 18 closing high, ahead of Thursday’s earnings.
- Analysts expect adjusted EPS of $4.11 on revenue of $4.1 billion, up 47% from a year ago.
- Morgan Stanley kept an Overweight rating but cut its price target to $643 from $676.
- A Nikkei report that Toshiba plans to double AI data center drive capacity hit both WDC and Seagate earlier this month.
- Insiders sold $11.0 million of stock in the past three months, while institutions own 92.51% of the company.
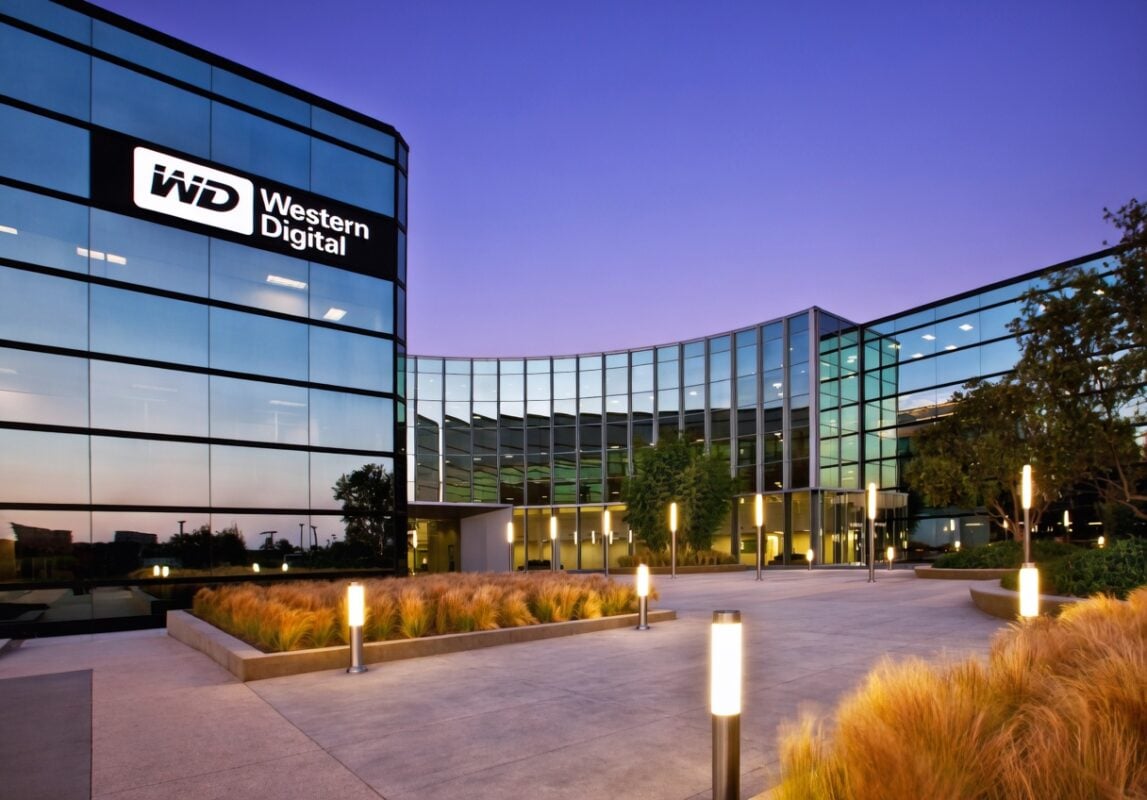
Western Digital (WDC) stock opened at $378.51 on Thursday, a day when the company reports earnings after the close. Another report put the price at $376.07, nearly 50% below the all-time closing high set on June 18. The stock rose about 4% on the day.
Western Digital Corporation, WDC
The drop has been steep for a stock that is still up roughly 750% since the start of 2024. The 52-week range runs from $117.23 to $799.87. Worries about an AI bubble drove much of the second-half slide.
Wall Street expects adjusted earnings of $4.11 a share for the September quarter. That compares with $1.78 a year ago. Revenue is forecast at $4.1 billion, up 47% from last year.
The company’s own guidance for the quarter was 3.850 to 4.150 in EPS. Management also pointed to revenue growth of 42% to 49%. The consensus sits near the top of that range.
Western Digital has a habit of beating estimates. In August, it reported EPS of $3.56 against a $3.31 forecast. Revenue came in at $3.75 billion versus $3.70 billion expected.
That pattern cuts both ways. Revenue tends to edge past forecasts, while earnings often beat by a wide margin. So a solid headline may not be enough to lift the stock.
What Analysts Want to Hear
Morgan Stanley analyst Erik Woodring said the stock trades at 15 times projected 12-month earnings. That is down from as high as 43 times in June. He argues the market is pricing in a peak that the data does not show.
“We see no evidence of irrational pricing or capacity behavior,” he wrote. He wants strong hard-drive pricing guidance for the December quarter. Morgan Stanley also named Seagate a “Top Pick.”
Toshiba is the other open question. Nikkei reported that the Japanese supplier plans to double its capacity for AI data center drives in fiscal 2027. Toshiba declined to comment.
In theory, more supply gives customers leverage in contract talks. UBS analyst Timothy Arcuri said hyperscalers plan to push as much volume to Toshiba as they can. He added that Toshiba will find it hard to compete at the high-capacity end.
Other analysts remain positive. Bank of America raised its target to $800 with a Buy rating. MarketBeat lists a “Moderate Buy” consensus with an average target of $609.56.
Technical Picture
No price chart came with these articles, so there is no chart to analyze.
The stock trades below its 50-day average of $438.14 and its 200-day average of $480.05. That sets up a downtrend structure. Reports also describe the stock as stuck in a bear market after falling more than half from its high.
What to watch: a move back above the 50-day average near $438 would point to a recovery. A slip below the recent lows could extend the slide.
Insider activity has leaned one way. CEO Irving Tan sold 20,000 shares at $444.97 in August under a pre-arranged plan. Diversify Advisory Services raised its stake by 79.4% to 11,631 shares in the third quarter.
Western Digital reports after the close on Thursday, with guidance on hard-drive pricing and Toshiba’s impact on customer talks the main items on the call.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants