


TLDR
- Micron stock fell 5.25% Monday after Anthropic, OpenAI, and SpaceX CEOs called for a slowdown in AI development
- Goldman Sachs analyst James Schneider expects Micron to deliver “another strong quarter” with Q4 FY26 revenue of $51.9 billion
- Wall Street projects Q4 FY26 EPS of $31.14, up from $3.03 a year ago, with revenue expected to surge over 345%
- UBS estimates about 90% of nearly $1 trillion in AI capital expenditure between 2025 and 2027 is set to be spent on memory
- Wall Street holds a Strong Buy consensus on MU with an average price target of $1,563.93, implying 69% upside
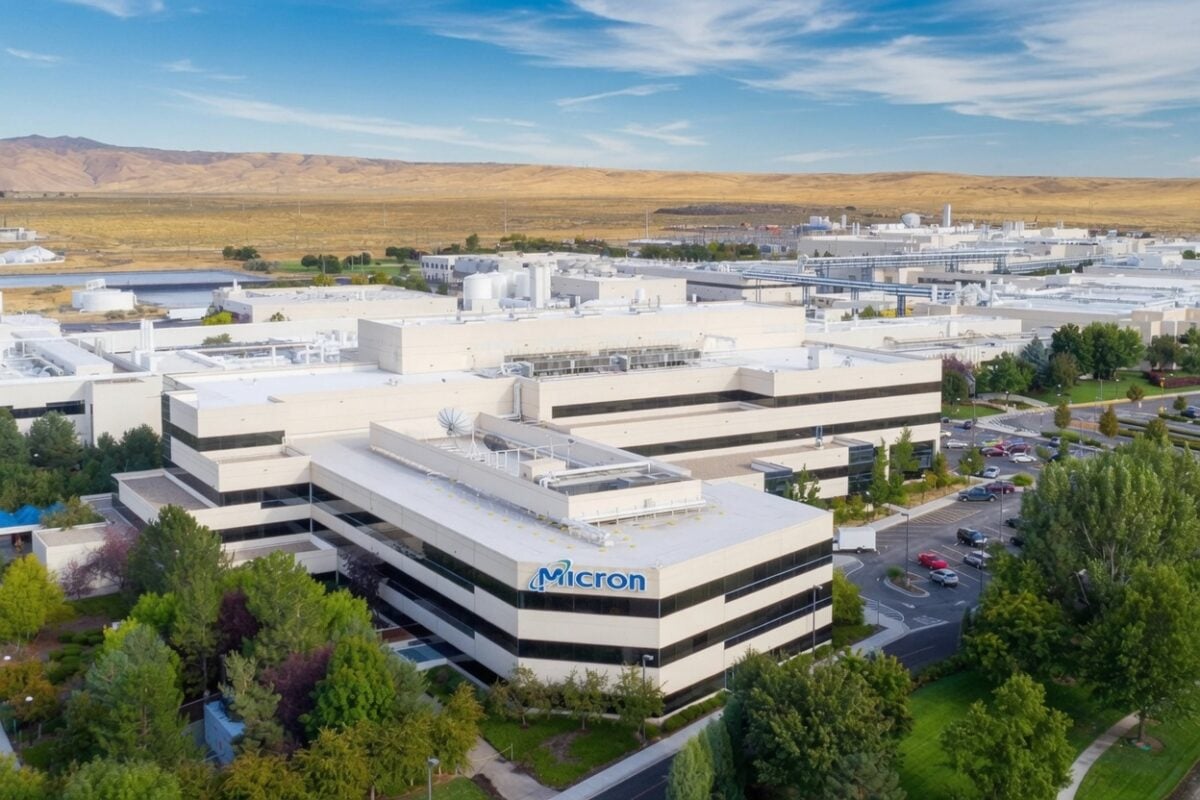
Micron stock dropped 5.25% to around $930.90 on Monday, adding to losses from the prior week and wiping out all of September’s gains. The sell-off came after the heads of Anthropic, OpenAI, and SpaceX publicly called for a slowdown in AI development over the weekend.
Peer SK Hynix ADRs also slid 6.9% on the same concerns.
Despite the dip, Goldman Sachs analyst James Schneider is staying constructive ahead of Micron’s Q4 FY26 earnings, scheduled for September 30. He expects the company to report “another strong quarter,” citing continued tightness in memory supply and demand.
Schneider raised his revenue and EPS estimates ahead of the report. He now expects Q4 FY26 revenue of $51.9 billion, about 3% above Wall Street’s consensus, along with EPS of $32.54 and a gross margin of 87.3%.
Wall Street’s consensus for Q4 FY26 EPS stands at $31.14, compared to $3.03 in the same quarter a year ago. Revenue is expected to jump more than 345% to $50.42 billion, driven by AI-related demand and higher memory pricing.
What Goldman Sachs Is Watching
Schneider noted that investors are watching two things closely: whether Micron can maintain or grow its roughly 20% share in high-bandwidth memory (HBM), and whether the company announces new strategic customer agreements with favorable pricing terms.

The analyst’s calendar year 2026 revenue and EPS estimates sit 1% and 3% above the Street’s numbers, respectively. He expects Micron to guide for low-teens quarter-over-quarter revenue growth for Q1 FY27.
Despite the positive outlook on the quarter, Schneider holds a Hold rating on MU with a price target of $1,100, citing a balanced risk-reward profile. He also flagged longer-term concerns around supply additions from rivals, particularly in China.
Why the Stock Dropped
The catalyst for Monday’s sell-off was a wave of AI safety commentary. The CEOs of Anthropic, OpenAI, and SpaceX all made public statements over the weekend calling for a pause or slowdown in AI development.
For Micron specifically, any sign of reduced AI infrastructure spending is a direct threat. UBS estimates that roughly 90% of the nearly $1 trillion increase in AI capital expenditure projected between 2025 and 2027 is earmarked for memory.
UBS economist Arend Kapyteyn wrote that AI capital spending is expected to reach nearly $1 trillion this year, rising to around $1.4 trillion by 2027, with memory costs absorbing a growing share.
Still, no major AI company has moved to cut actual capital spending. The Trump administration continues to back the data-center buildout, and Anthropic itself is reportedly pushing ahead with IPO plans that could value the company at $2 trillion.
Nancy Tengler, CEO and CIO at Laffer Tengler Investments, said she used the dip to add to her Micron position, noting that the data center buildout backlog remains firmly in place.
MU stock has rallied 224% year-to-date and is up more than sixfold over the past 12 months.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants