


TLDR
- The U.S. dollar pulled back slightly Wednesday but stayed near multi-week highs ahead of a Federal Reserve rate decision.
- Markets are pricing in a 92% chance the Fed raises rates by 25 basis points to a 3.75%-4.00% range.
- Fed Chair Kevin Warsh’s press conference guidance will be key, with traders watching whether hikes are a one-off or a series.
- The Japanese yen strengthened slightly, with an 80% chance priced in for a Bank of Japan rate hike Friday.
- Oil prices above $113 a barrel, driven by attacks on Saudi infrastructure and Red Sea disruptions, are fueling the inflation concerns behind the tightening cycle.
The U.S. dollar eased slightly on Wednesday for the first time in seven sessions, pulling back from near multi-week highs as currency markets paused ahead of a Federal Reserve interest rate decision expected later in the day.
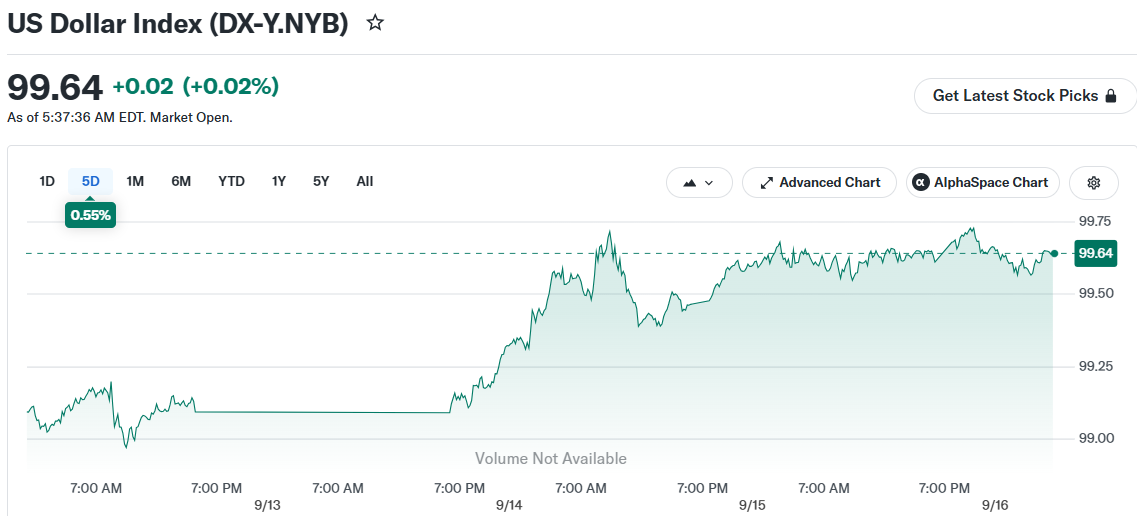
The Dollar Index, which tracks the greenback against six major currencies, was nearly flat at around 99.59 after several days of gains.
Financial markets have priced in a 92% probability that the Fed will raise its benchmark rate by 25 basis points, moving it into a 3.75%-4.00% range. This would mark the first U.S. rate hike since mid-2023.
The rate hike is widely expected. What traders are really watching is what Fed Chair Kevin Warsh says after the decision.
Markets want to know whether Warsh will frame the hike as a one-time move to guard against high oil prices, or signal the start of a run of consecutive increases.
A dovish tone could push the dollar lower as traders take profits. A hawkish signal pointing to more hikes ahead could push it higher.
Energy Prices Driving Inflation Concerns
Crude oil has climbed past $113 a barrel following attacks on Saudi Arabian pipeline infrastructure and Houthi strikes in the Red Sea. Those supply disruptions have pushed energy prices higher and stoked inflation, giving central banks reason to tighten policy.

ANZ analysts told clients they expect the Fed to raise rates at back-to-back meetings, though they noted the October meeting falls close to U.S. midterm elections.
The euro was flat near $1.1554, not far from a one-month low. The European Central Bank raised its deposit rate by 25 basis points last Thursday to 2.50%, also responding to energy-driven inflation.
The British pound held around $1.3483. U.K. inflation rose to 3.1% in August from 2.9% in July, with core inflation steady at 2.6%. The Bank of England announces its rate decision on Thursday. Traders see a one-in-three chance of a 25-basis-point hike.
Yen Strengthens, Bank of Japan Eyed
The Japanese yen recovered after hitting a one-week low of 155.49 per dollar earlier in the session. It edged back to around 154.97 yen per dollar by midday.
Markets are pricing in an 80% chance that the Bank of Japan raises its policy rate by 25 basis points to 1.25% on Friday. Two hikes are priced in by the end of January.
The yen has been boosted by a hawkish shift in Bank of Japan expectations, joint U.S.-Japan currency intervention, and Japanese investors bringing capital home.
Julius Baer economist David Meier said the yen’s path will continue to depend heavily on interest rate differentials and revised the bank’s USD/JPY forecast to 155.
China’s yuan held near 6.71 per dollar despite a widening gap between Chinese yields and rates in other major economies.
All eyes remain on Warsh’s press conference as the single biggest catalyst for the dollar’s next move.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants