


TLDR
- Q2 sales rose 17.6% to $2.03 billion, broadly in line with analyst estimates
- Comparable store sales in Canada grew 5.4%, up from 4.9% a year ago
- EBITDA margin narrowed to 32.2% from 34.1%, dragged lower by the Australian business
- Dollarama raised its annual Canadian comparable sales growth forecast to 4%-4.5%, from 3%-4%
- The stock is down roughly 19% year-to-date, and fell a further 1.69% on Wednesday
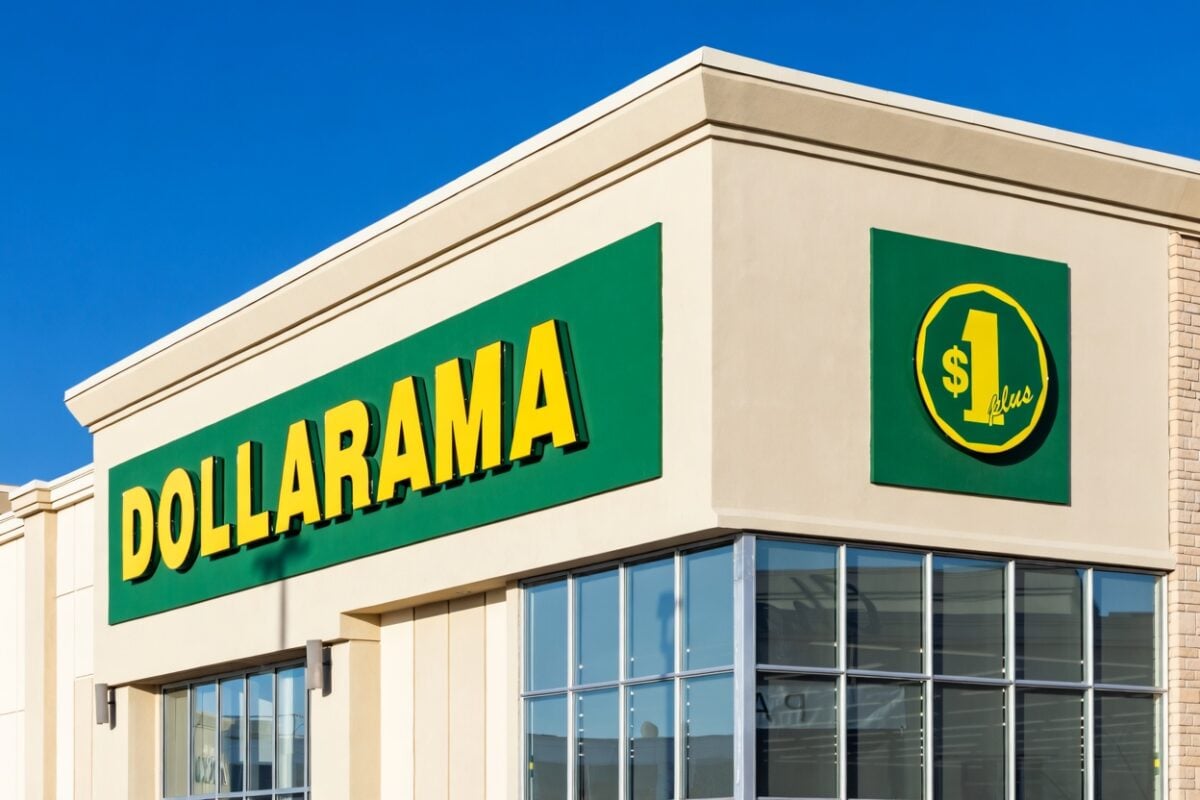
Dollarama (TSX: DOL) reported second-quarter fiscal 2027 results on Wednesday, posting sales of $2.03 billion, a 17.6% increase from $1.72 billion in the same period last year. The result came in broadly in line with analyst expectations.
The stock dropped 1.69% on the day, extending a year-to-date decline of roughly 19%.
Diluted earnings per share came in at $1.29, up 11.2% from $1.16 a year ago. Net earnings rose 8.7% to $349.3 million for the quarter.
Canadian comparable store sales grew 5.4%, driven by a 3.7% increase in transaction volume and a 1.7% rise in average basket size. That builds on 4.9% growth in the same quarter last year.
Demand for consumables and general merchandise was cited as the primary driver of traffic growth in Canada.
Margins Feel the Weight of Australia
EBITDA margin contracted to 32.2% from 34.1% a year ago, largely due to the inclusion of a full quarter of results from Dollarama Australia. The prior year comparison only included 13 days of Australian operations following the acquisition of The Reject Shop.

Australian operations carry a lower gross margin and higher SG&A as a percentage of sales compared to the Canadian business, each adding roughly 110 basis points of drag.
In Canada alone, EBITDA margin improved to 34.9% from 34.5%, showing the domestic business remains healthy.
The company opened 15 net new stores in Canada during the quarter, down from 27 in the same period last year. In Australia, four net new stores were opened and 25 locations were renovated.
Dollarama also repurchased 1,596,016 common shares for $300.4 million during the quarter.
Guidance Lifted on Stronger Canadian Demand
Dollarama raised its annual comparable store sales growth forecast for Canada to 4%-4.5%, up from its prior guidance of 3%-4%.
CEO Neil Rossy pointed to consumer behaviour as a key tailwind, noting that customers are “making careful spending decisions” and turning to Dollarama for value.
The Dollarcity business, which covers Central and South America and Mexico, also showed momentum. Sales from that segment rose 30% year-over-year, with store count growing from 658 to 781 locations over the past 12 months.
Net financing costs increased by $8.0 million to $51.2 million, reflecting higher average debt levels following two fixed-rate note issuances in the first quarter.
Dollarama’s updated store opening guidance, alongside the raised comparable sales forecast, was confirmed alongside the earnings release on Wednesday.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants