


TLDR
- Vera Therapeutics stock rose 4% to $35.39 after releasing two-year trial data for its kidney drug Trutakna
- Trutakna slowed kidney decline to match normal aging rates in patients with IgA nephropathy
- Vera plans to file a supplemental Biologics License Application in Q4 to secure full FDA approval
- TD Cowen reiterated a Buy rating with a $78 price target following the trial results
- VERA stock is still down 34% in 2026, facing pressure from rivals Vertex and Otsuka
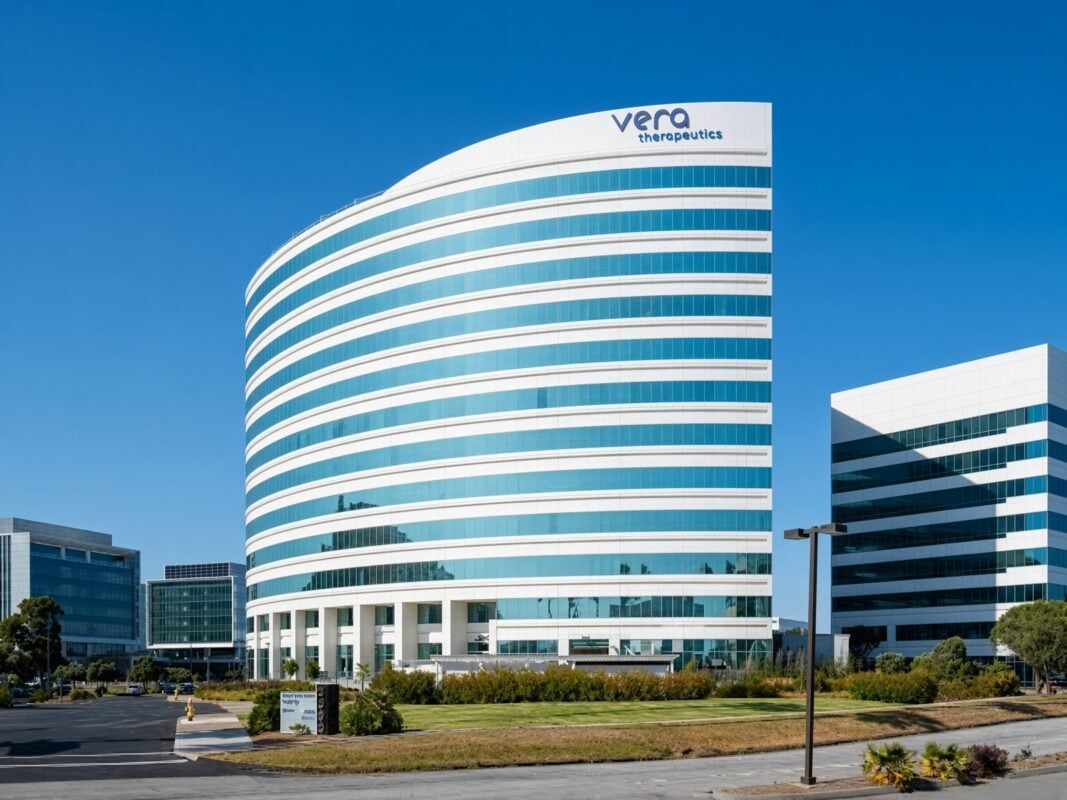
Vera Therapeutics stock climbed 4% to $35.39 on Tuesday after the company released two-year data from its ORIGIN3 trial for kidney drug Trutakna, giving investors a reason to buy into a name that has struggled in 2026.
The trial focused on patients with immunoglobulin A nephropathy, a condition where abnormal antibody buildup damages the kidneys’ filtering units. The results showed Trutakna slowed kidney decline to a rate matching normal aging, which is the benchmark for successful treatment.
The annualized eGFR slope delta reached +5.0 mL/min/year versus placebo. Trutakna drove a two-year annualized eGFR decline of just -0.6 mL/min/year, a rate consistent with what you would expect in a healthy population.
TD Cowen reiterated its Buy rating and $78 price target on the back of the data, calling the kidney function dataset among the most compelling generated in a Phase 3 IgAN trial.
That number was also numerically superior to the +4.5 mL/min/year placebo-adjusted benefit seen with rival drug Voyxact, though TD Cowen acknowledged the difference could fall within normal measurement variability.
Patients also showed improvement in key disease markers, including lower levels of excess protein and blood in their urine. Stanford nephrology professor and trial investigator Richard Lafayette said the data provides strong evidence that Trutakna can reduce long-term risks of dialysis, transplant, or death.

Full FDA Approval in Sight
Trutakna received accelerated FDA approval in July, based on its ability to reduce protein levels in urine. To convert that to full approval, Vera must now submit confirmatory data showing long-term clinical benefit.
The company plans to file a supplemental Biologics License Application in Q4. Chief Commercial Officer Matt Skelton noted that in the first 10 weeks since launch, Vera generated over 350 patient start forms and has already seen paid claims come through.
Analyst price targets range from $34 to $100, with the broader consensus sitting at Strong Buy. Raymond James maintained a Strong Buy with an $84 target, while Goldman Sachs holds a Buy rating with an $80 target after lowering it slightly. H.C. Wainwright trimmed its target to $90 from $125, citing competitive data from a rival therapy.
Competitive Pressure Remains
Despite Tuesday’s move, VERA is still down 34% year-to-date, weighed down by a crowded field in IgAN treatment.
Otsuka launched Voyxact in late 2025 through accelerated approval. While both drugs target the same disease, Voyxact focuses on a single protein, while Trutakna targets two distinct proteins.
Vertex is developing its own dual inhibitor, povetacicept, with a BLA accepted for accelerated approval and a target action date of November 30. Rival Vertex stock dipped 1% on Tuesday.
The company holds more cash than debt on its balance sheet, which TD Cowen and InvestingPro both flagged as a key advantage for a clinical-stage biotech.
Stop guessing and start investing with confidence. KnockoutStocks gives you the AI insights, market intelligence, and stock research you need to spot opportunities, cut through the noise, and make smarter investment decisions — all in one powerful platform.
Sign up today and get 50% OFF full access to our premium stock picks.
Simply use coupon code SPECIAL50 at checkout to claim your exclusive discount.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants